
U.S. New-Home Sales Fall in September as Mortgage Costs Weigh on Buyers
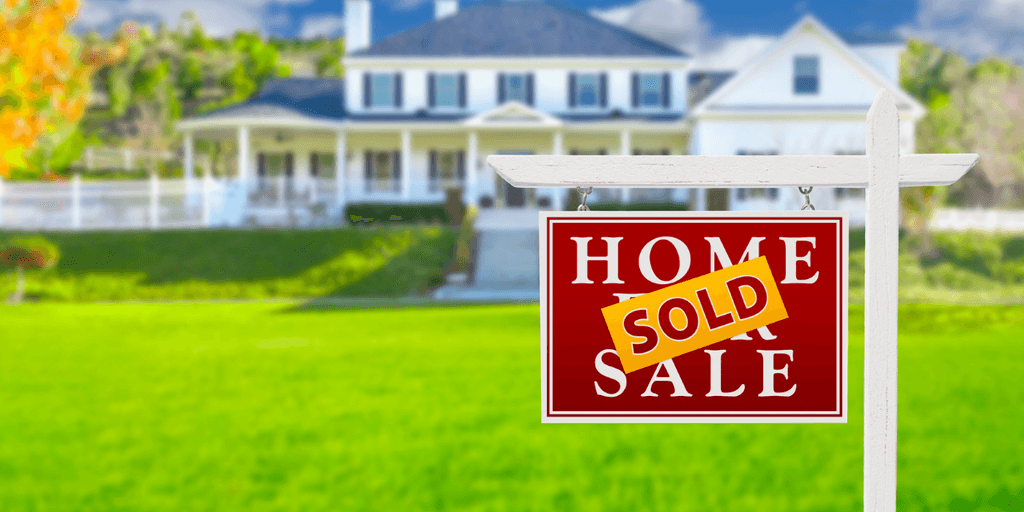
New-home sales declined from August and a year earlier, while lower median prices and builder incentives reflected continued affordability pressures.
Sales of new single-family homes in the United States declined in September, according to federal data released on October 27, adding to evidence that elevated borrowing costs continue to challenge prospective homebuyers. The report showed that builders are adjusting prices and offering incentives as they attempt to attract customers in a market where monthly mortgage payments remain a significant barrier.
The Census Bureau and the Department of Housing and Urban Development estimated that new-home sales ran at a seasonally adjusted annual rate of 676,000 in September. That was 0.6% below August's revised rate of 680,000 and 5.3% below the level recorded a year earlier.
The monthly decline was smaller than economists had expected, but the year-over-year decrease pointed to continued pressure on housing demand.
Median New-Home Price Declines
The median price of a new home sold in September was $400,400, down 3.9% from a year earlier. The average price also declined, reflecting changes in both market conditions and the mix of homes being purchased.
Lower prices can help buyers who have struggled to find homes within their budgets, but they do not necessarily translate into lower monthly payments for every household. Mortgage rates, property taxes, insurance, maintenance and other expenses all influence affordability.
A buyer considering a home must assess the total cost of ownership rather than relying on the purchase price alone. Higher financing costs can offset some of the benefit from a lower sale price, particularly for households with limited down-payment savings.
Builders have responded by adjusting prices, offering financing incentives and bringing more homes to lower price points. These measures can make certain properties more accessible, but they also indicate that sellers are working harder to attract demand.
Mortgage Rates Continue to Influence Demand
The average rate on a 30-year fixed mortgage reached 7.32% in the week ending October 22, according to Freddie Mac data cited in housing market reporting. The rate was substantially higher than the comparable level a year earlier.
Mortgage rates affect how much buyers can borrow while keeping payments within their budgets. When rates rise, a household that qualifies for a particular loan amount may find that the same payment supports a smaller mortgage.
That can lead prospective buyers to postpone purchases, seek less expensive properties or reconsider the size and location of the home they can afford.
Higher rates also affect existing homeowners who have mortgages at lower rates. Some may be reluctant to sell and take on a new loan at a higher rate, limiting the number of existing homes available in certain markets.
The resulting market can be difficult for both buyers and sellers, with affordability constraints reducing demand even when available inventory offers more choices.
Inventory Gives Buyers More Options
The number of new homes available for sale at the end of September was estimated at 476,000, down about 1% from August. At September's sales pace, that represented an 8.4-month supply.
Months of supply is a measure of how long the available inventory would last if homes continued selling at the current rate. It does not predict exactly how the market will behave, but it helps indicate the balance between available properties and buyer demand.
A higher supply can give buyers more opportunity to compare properties and negotiate. It can also require builders to offer concessions to prevent inventory from remaining unsold for extended periods.
The figures varied by region, with sales changes reflecting different local conditions. Employment, population growth, construction costs and regional housing supply can all influence demand. National statistics therefore provide an overview rather than a complete picture of conditions in every city.
Builders Offer Incentives to Maintain Sales
Builder confidence has weakened as buyers respond to financing costs and affordability pressures. Industry survey data released around the same period indicated that 43% of builders had reduced prices in October, while 65% offered sales incentives.
Incentives can include mortgage-rate buydowns, closing-cost assistance, upgrades or other concessions. Such offers can help buyers manage upfront costs or monthly payments, although the terms differ by builder and property.
Builders also face decisions about which types of homes to construct. Smaller homes and lower-priced properties may reach a broader group of buyers, while larger or more expensive homes can become harder to sell when borrowing costs are high.
The September data showed that homes priced below $400,000 represented a larger share of new-home sales than a year earlier. That shift suggests that affordability is influencing what buyers purchase as well as how many homes they buy.
Implications for the Wider Housing Market
New-home sales are one part of the U.S. housing market. Existing-home sales, rental demand, construction activity and mortgage applications provide additional information about how households are responding to financing costs and available supply.
When homeownership becomes harder to afford, some households may remain renters for longer. Others may move to less expensive areas or delay forming independent households. These choices can affect local housing demand, although rental conditions depend on separate factors, including apartment construction, employment and population movement.
For policymakers and housing professionals, the latest report highlights the difficulty of improving affordability through any single measure. More homes can expand choice, but buyers also need financing options and prices that fit household budgets.
A Market Still Adjusting
The September sales figures show that the housing market continues to adjust to a combination of borrowing costs, inventory and buyer purchasing power. Builders are using price reductions and incentives to maintain sales, while prospective homeowners must weigh the cost of financing against their long-term housing needs.
The relatively small monthly decline offered some evidence of resilience, but the annual decrease and lower median price demonstrated that challenges remain.
For households considering a purchase, the most relevant indicators will include local prices, mortgage terms, available inventory and the full cost of ownership. For builders, sustaining demand will depend on matching homes and financing options to what buyers can realistically afford.

Good Morning US Contributor
Covers national politics and policy, with an eye on how decisions in Washington reach everyday households.
This article features partner, contributor, or branded content from a third party. Members of the Good Morning US editorial staff were not involved in the creation of this content. All views and opinions are those of the contributor alone.
You May Also Like
Memorra: Best AI Powered Memory Preservation Service in the USA of 2026
How ORYN Quest Uses AI to Help Parents Discover Kids’ Activities and Support Their Growth
Kranay Academy Is Taking the Guesswork Out of Scholarships With 3 FREE Personalized Matches
Federal Reserve Holds Interest Rates Steady as Inflation Remains Elevated
Oregon Seafood Plant Fire Triggers Evacuations After Ammonia Leak on Newport Bayfront